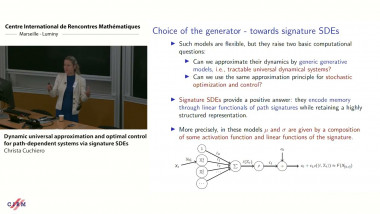
Dynamic universal approximation and optimal control for path-dependent systems via signature SDEs
Many applications in generative time series modeling, particularly in finance, require stochastic dynamics that are genuinely path-dependent and non-Markovian.
From a numerical perspective, the most natural route is to lift path dependence to an enlarged state space, thereby obtaining a Markovian approximation of the original dynamics.
Among such lifts, signature SDEs provide a canonical and model-agnostic choice, building on the strong algebraic and approximation-theoretic properties of path signatures, which form a universal and non-parametric feature set for paths.
We explain how this leads to dynamic universal approximation results for generic non-Markovian SDEs. We also show how the resulting finite-dimensional signature SDEs can be used in optimal control problems with path-dependent dynamics and objectives.