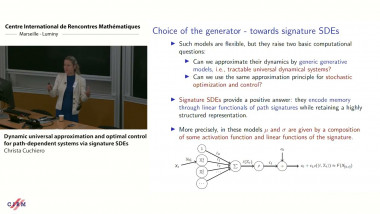
Dynamic universal approximation and optimal control for path-dependent systems via signature SDEs
De Christa Cuchiero
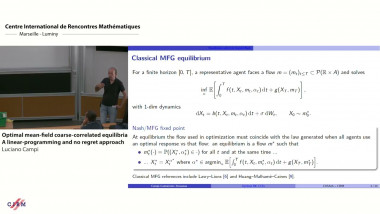
Optimal mean-field coarse-correlated equilibriaa linear-programming and no-regret approach
De Luciano Campi
Apparaît dans les collections : Exposés de recherche, CEMRACS - Summer school: Numerical methods for stochastic models: control, uncertainty quantification, mean-field / CEMRACS - École d'été : Méthodes numériques pour équations stochastiques : contrôle, incertitude, champ moyen
We analyse how reverting Random Number Generator can be efficiently used to save memory in solving dynamic programming equation. For SDEs, it takes the form of forward and backward Euler scheme. Surprisingly the error induced by time reversion is of order 1.