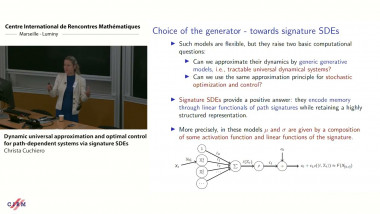
Dynamic universal approximation and optimal control for path-dependent systems via signature SDEs
De Christa Cuchiero
Optimal mean-field coarse-correlated equilibriaa linear-programming and no-regret approach
De Luciano Campi
Apparaît dans la collection : A Random Walk in the Land of Stochastic Analysis and Numerical Probability / Une marche aléatoire dans l'analyse stochastique et les probabilités numériques
The Cox Construction of a totally inaccessible stopping time with a given compensator is ubiquitous in Mathematical Finance, and in particular in Credit Risk. On the other hand, as P.A. Meyer showed long ago, totally inaccessible stopping times arise naturally as the jump times of a strong Markov process. We relate the two ideas and propose a solution to a question posed by Monique Jeanblanc.